At a glance
- Thailand’s policy instrument is the one-day bilateral repurchase rate. [2]
- Loan contracts and credit risk determine how much of a rate change reaches borrowers. [4][5]
- Currency and tourism effects are conditional, while economy-wide effects arrive with a lag. [7][8][9][10]
One decision, several prices
A policy-rate announcement does not reset every financial contract in Thailand. The Bank of Thailand uses monetary policy to pursue price stability over the medium term, sustainable growth and financial stability. Its policy rate is a price within the financial system: the one-day bilateral repurchase rate. The rate on a mortgage or a savings account is a separate price, reached through further decisions. [1][2]
The first stage operates among financial institutions. The BOT uses repurchase and reverse-repurchase transactions to add or absorb bank reserves temporarily. Together with its other monetary operations, this helps steer short-term market rates. Banks then confront changed funding conditions, but the next step depends on their pricing and on the borrower’s contract. [3][11]
The contract is the transmission mechanism
Thai loan documents commonly refer to floating benchmarks such as MLR, MOR and MRR. The BOT explains that banks use these reference rates for different lending categories and may charge a margin above or below them. A floating-rate borrower can therefore be affected when the relevant bank benchmark changes. A fixed rate remains fixed for the agreed period. [4]
Illustration: if the actual annual interest rate on an unchanged one-million-baht balance falls by 0.25 percentage point, simple annual interest falls by 2,500 baht. That is arithmetic under stated assumptions, not a prediction of a monthly instalment. An amortising balance, a fixed-rate period, fees or a different repricing date can change the result. Crucially, the example concerns the loan’s own rate; a policy cut does not guarantee the same reduction. [4]
Cheaper credit and available credit are different questions
The BOT’s fourth-quarter 2025 Monetary Policy Report provides a useful historical test. For the 2024–25 easing cycle it examined, transmission to commercial-bank reference lending rates averaged 57 percent. Contract-level analysis found smaller reductions for SMEs and retail borrowers than for larger businesses, partly reflecting differences in credit risk and bargaining power. These are observations from that period, not fixed conversion factors for future decisions. [5]
A lender can lower a posted rate while remaining reluctant to approve a particular application. A business with uncertain sales may also postpone investment despite cheaper borrowing. The policy decision influences financing conditions; it cannot by itself supply a reliable customer base or remove the risk that a loan will not be repaid. That is why lending volumes and lending prices deserve separate attention. [5]
The saver feels another side of the change
The same 2025 BOT analysis found that deposit rates also fell, with different responses across savings and fixed-term products. [5] Timing matters for savers: a renewal can expose money to a new rate. Bangkok Bank’s published fixed-deposit conditions provide a concrete example, specifying rollover at the rate available on maturity unless the customer gives other instructions. This illustrates a contract mechanism, not a product recommendation. [6]
Lower financing costs and lower interest income can coexist. The effect on household spending therefore depends on the household’s combination of debts, deposits and other income. A single headline rate cannot describe every household’s experience.
The baht does not obey a single switch
Interest rates can influence demand for baht assets by changing returns relative to foreign investments. A cut can consequently create downward pressure on the currency, other things equal. But the exchange rate also reflects expectations and cross-border flows. Thailand operates a managed float: the market determines the baht, with possible BOT intervention against excessive volatility. [7][1]
For a concrete historical example, the BOT’s May 2024 review linked movements in the baht to US economic releases, expectations about Federal Reserve policy and Thailand’s growth figures. An unchanged Thai policy rate can accompany a changing exchange rate, and an anticipated cut may provoke less market reaction than an unexpected signal. Reading the decision requires reading what markets already expected. [8][7]
Tourism adds a two-way relationship
Illustration: if a visitor receives more baht for the same foreign-currency budget while Thai prices stay unchanged, that budget buys more locally. The effect can support tourism spending, but does not establish how many people will travel. Visa access and other conditions matter too: the BOT linked part of May 2024’s increase in arrivals to visa and land-entry facilitation. [8]
The relationship also runs back toward the currency. The BOT attributed part of the baht’s December 2024 strength to higher seasonal tourism revenue. Tourism both responds to financial conditions and generates flows that can change them. It is therefore misleading to translate a rate cut directly into a forecast for hotel occupancy. [9]
Allow time for the wider effect
A BOT model presented in October 2025 put the peak effect on economic activity and inflation around four to six quarters after a policy change. That is a model result, not a countdown applicable to every cycle. [10] A useful reading of monetary policy follows the sequence from market rates to contracts, credit decisions and spending, while allowing for shocks along the way. The headline decision starts the inquiry; it does not settle the outcome.
What to know
Follow the actual loan or deposit rate, its contract terms and the availability of credit. Treat exchange-rate and tourism effects as conditional, and distinguish a historical transmission estimate from a forecast.
About this reporting
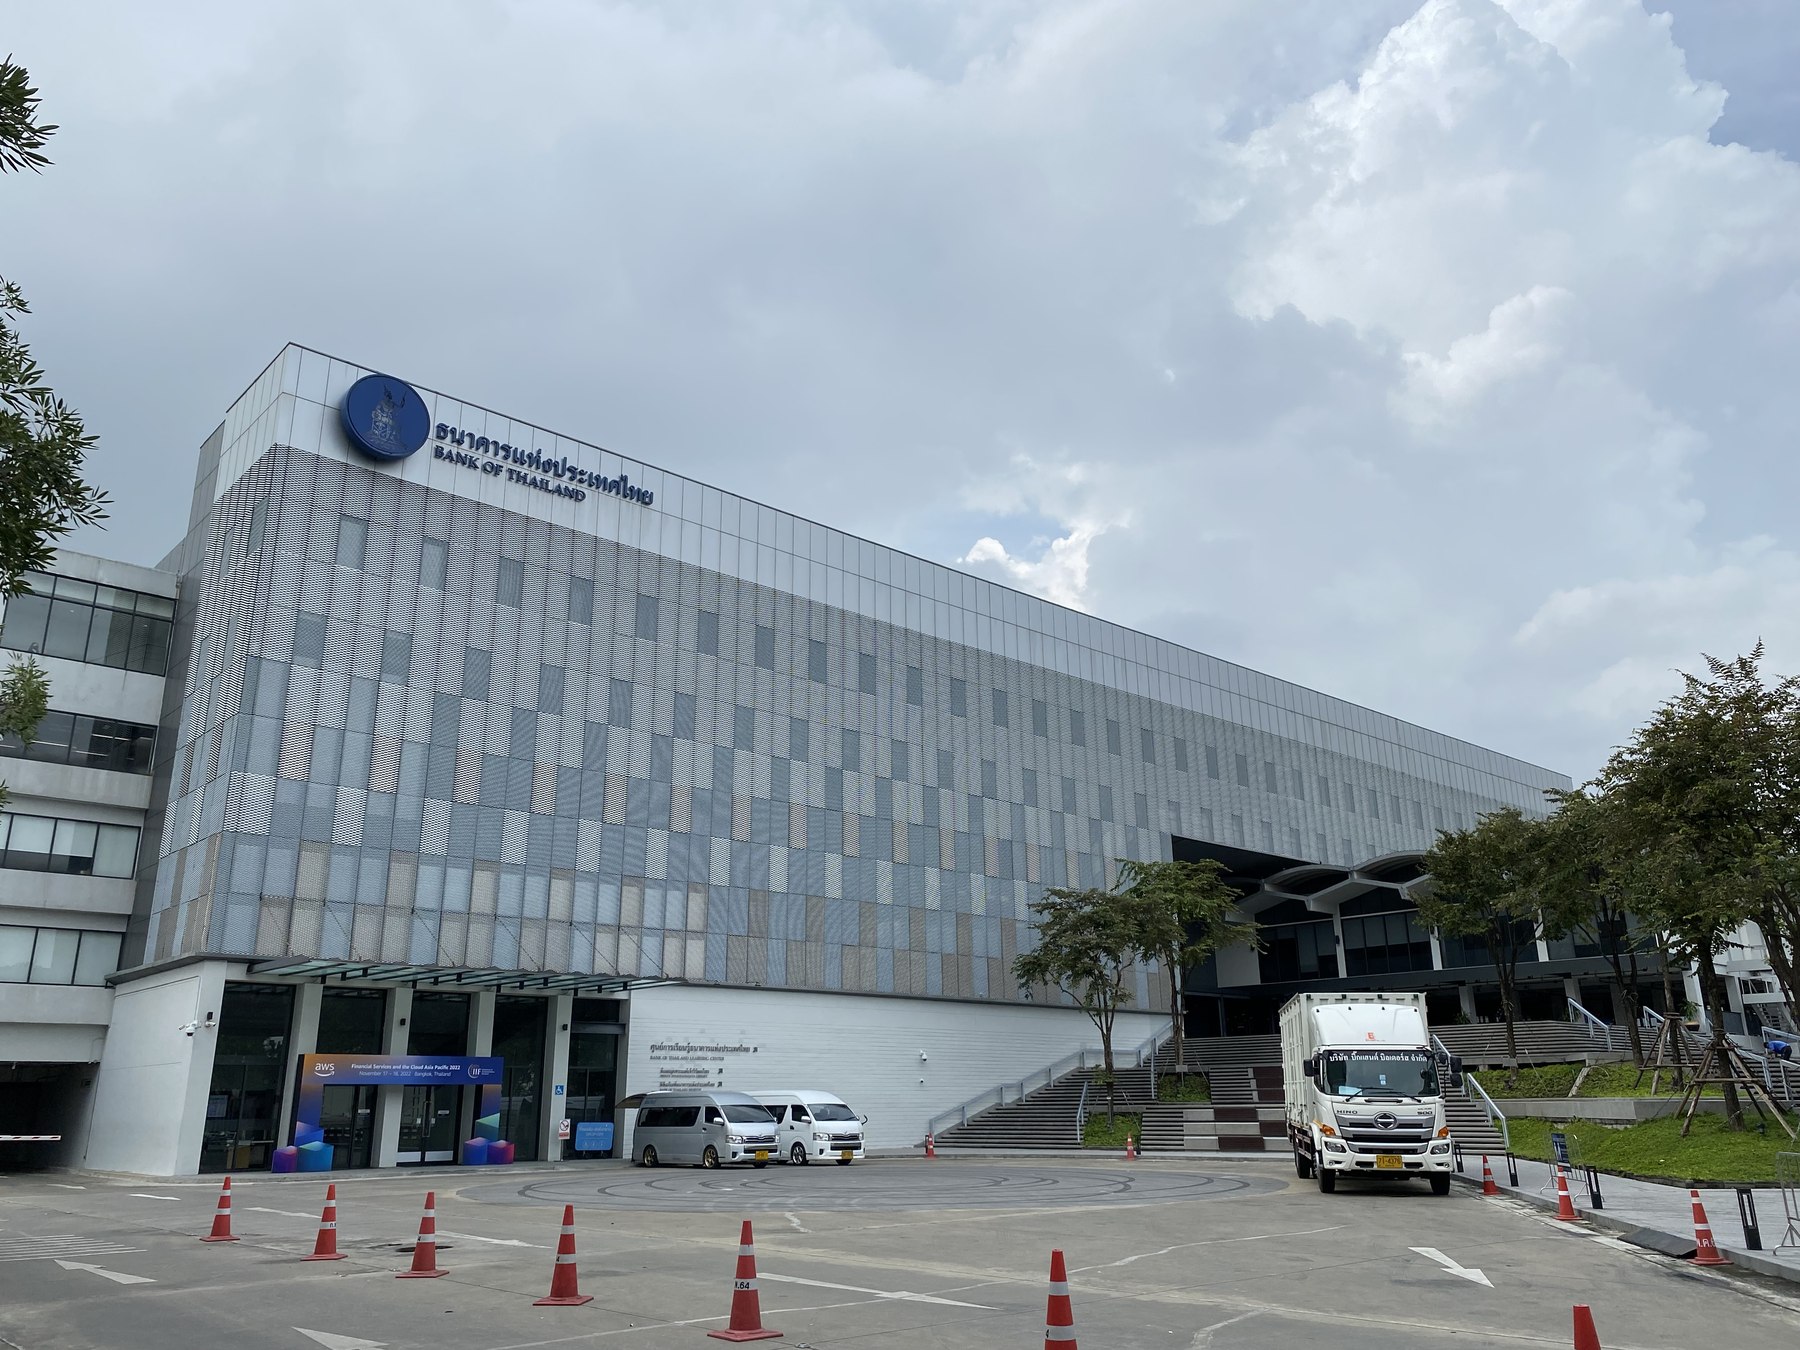
AI-assisted research and drafting from the linked sources, with original explanatory analysis. No interviews or field visits are claimed. Photographs are dated archive images. Historical and model results describe their stated periods; they are not current rate quotations or forecasts.
Corrections & updates
: Expanded with additional primary sources, analysis and licensed photographs. Original publication date retained.
: Corrected sentence capitalization; reporting and original publication date are unchanged.